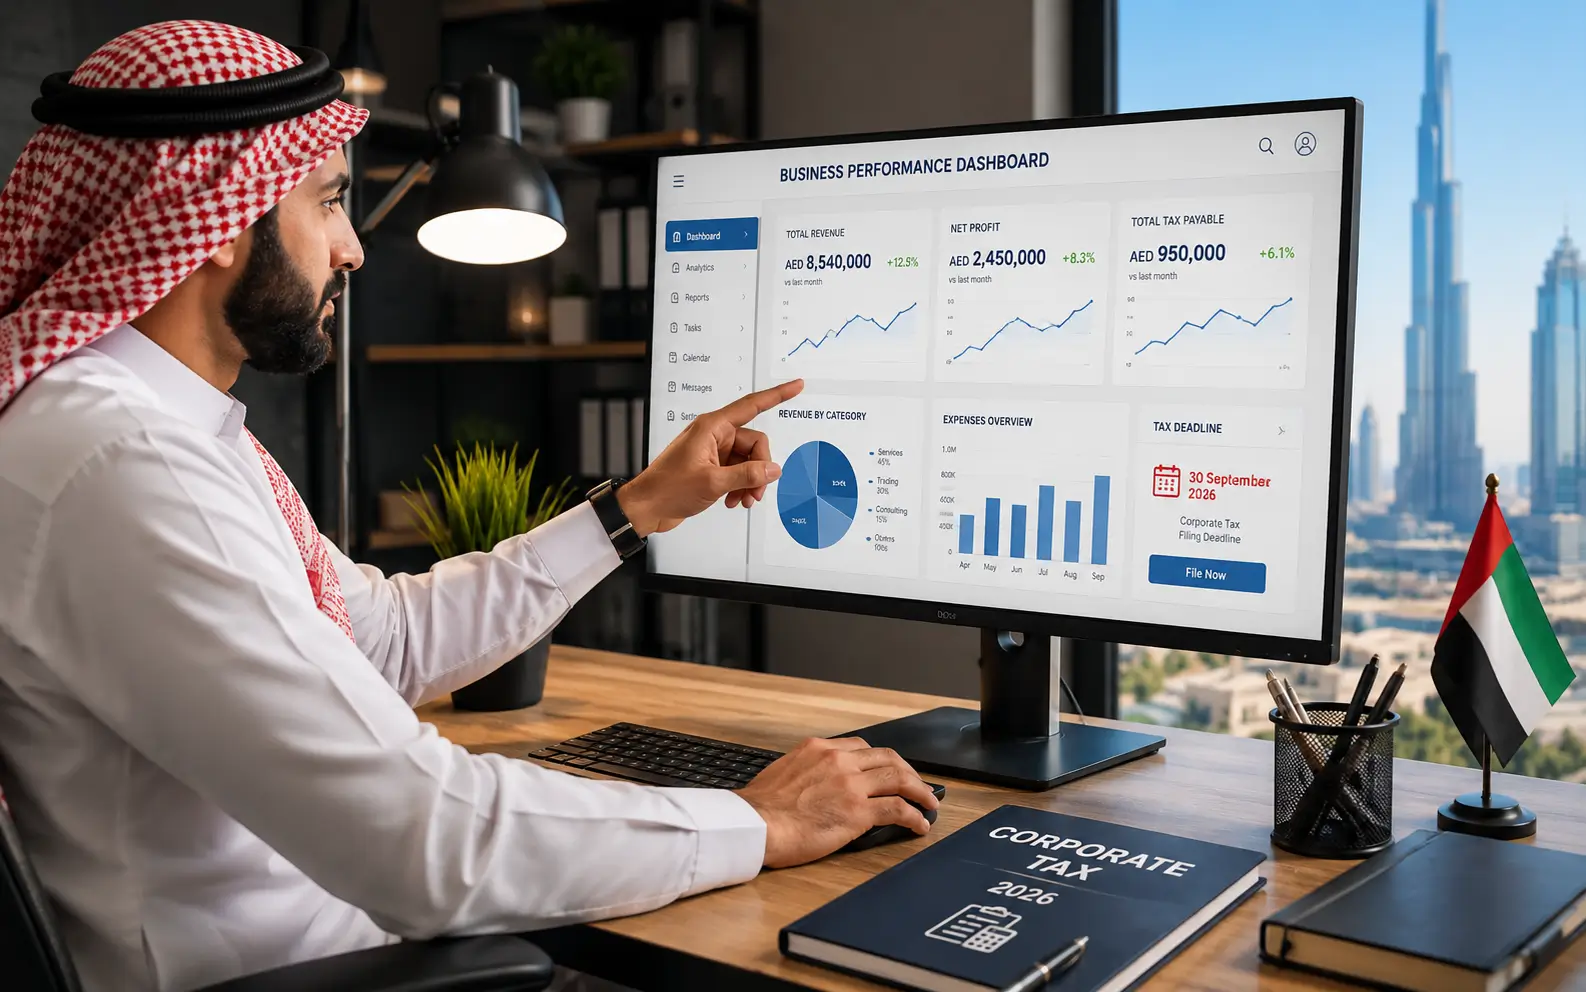
The clock is officially ticking. If your company’s financial year ended on 31 December 2025, your UAE corporate tax return must be filed and any tax due must be paid by 30 September 2026. No extensions. No grace period. And the Federal Tax Authority (FTA) has made one thing crystal clear: missing this deadline triggers automatic penalties, even if your business owes zero tax.
Here’s the part that catches most Dubai business owners off guard: this isn’t just a “big company” problem. Mainland LLCs, free zone entities, and even freelancers with revenue above AED 1 million all fall under the corporate tax net. If you hold a trade licence in the UAE, this deadline almost certainly applies to you.
In this guide, we break down exactly what you need to do before 30 September in plain English, without the jargon.
First Things First: Does the 30 September Deadline Apply to You?
The rule under Federal Decree-Law No. 47 of 2022 is simple: every taxable person must file a corporate tax return and pay any tax due within nine months of the end of their financial year. Because most UAE businesses follow the January December calendar year, 30 September 2026 is the deadline that applies to the vast majority of companies in Dubai.
| Financial Year End | Filing & Payment Deadline |
| 31 December 2025 | 30 September 2026 |
| 31 March 2026 | 31 December 2026 |
| 30 June 2026 | 31 March 2027 |
Important: free zone companies enjoying the 0% qualifying rate must still file a return. Filing is mandatory for everyone; the 0% rate is a tax rate, not an exemption from compliance.
What Happens If You Miss the Deadline? (Spoiler: It Gets Expensive Fast)
The FTA’s penalty structure is designed to make procrastination painful. Here’s what late businesses face:
- Late filing: AED 500 per month for the first 12 months of delay, rising to AED 1,000 per month thereafter.
- Late payment: annual interest of 14% on the unpaid tax amount charged on top of the filing penalty.
- Incorrect returns: errors discovered by the FTA cost significantly more than errors you disclose voluntarily, so getting the numbers right the first time matters.
These penalties run in parallel and are not capped at a single fixed maximum. A return filed a few months late with an unpaid balance can quickly snowball into five figures. Also note that the updated penalty regime under Cabinet Decision No. 129 of 2025 came into effect on 14 April 2026 so older blog posts quoting pre-2026 penalty rules may already be out of date.
Your 7-Step Action Plan Before 30 September
- Confirm your registration. You cannot file without a Tax Registration Number (TRN). Log in to EmaraTax and verify your corporate tax registration is active.
- Close and reconcile your books. Your return must reconcile to proper financial statements for the 1 January – 31 December 2025 period. Messy bookkeeping is the number-one cause of last-minute panic.
- Check whether you need an audit. Certain entities including qualifying free zone persons and larger businesses must maintain audited financial statements. If an audit is required, book it now; auditors’ calendars fill up fast in Q3.
- Review reliefs and elections. Small Business Relief (for revenue up to AED 3 million), transfer pricing rules, and free zone qualifying income conditions all need to be assessed before you file, not after.
- Calculate your liability. Corporate tax is 0% on taxable income up to AED 375,000 and 9% above that threshold. Deductions, exempt income, and adjustments all affect the final figure.
- File through EmaraTax. Complete the return in the corporate tax module, submit, and download your acknowledgement receipt as proof of filing.
- Pay early, not on deadline day. Payment counts only when the funds actually reach the FTA’s account, not when you initiate the transfer. The FTA has warned that transfers processed after the deadline still attract penalties. Aim to pay by 25 September at the latest.
The Costly Mistakes Dubai Businesses Keep Making
- Assuming free zone = no obligations. Even at 0%, you must register, keep records, and file on time.
- Waiting for a “tax invoice” from the FTA. Corporate tax is self-assessed. No one will send you a bill the responsibility to file and pay sits entirely with you.
- Ignoring record-keeping rules. Businesses must retain supporting records and documents for seven years. The FTA can request them during reviews or audits.
- Treating the deadline as “filing only.” 30 September is the deadline for both filing and payment. There is no separate, later payment window.
- Leaving it to September. Portal slowdowns, bank processing times, and consultant availability all get worse in the final weeks. The businesses that file in July and August sleep better.
Why Smart Business Owners Aren’t Doing This Alone
For many Dubai companies, this is only their first or second corporate tax cycle and the rules around transfer pricing, free zone qualification, deductible expenses, and reliefs are anything but intuitive. One misjudged election or misclassified expense can mean overpaying tax or, worse, facing FTA adjustments and penalties later.
That’s why a growing number of SMEs are handing the process to specialists. Experienced corporate tax consultants in Dubai can review your books, confirm which reliefs you qualify for, prepare and file the return through EmaraTax, and make sure payment lands with the FTA on time, typically for far less than the cost of a single month’s late penalty.
The Bottom Line
30 September 2026 is not a soft deadline it’s a hard cut-off with automatic financial consequences. But with roughly six weeks still on the clock, there’s ample time to get compliant without the stress. Reconcile your books, confirm your reliefs, file through EmaraTax, and pay early.
Do it now, and the deadline becomes a non-event. Leave it too late, and it becomes the most expensive date on your 2026 calendar. The choice and the clock is yours.